In today’s fast-paced financial landscape, individuals are constantly seeking more accessible means to secure funds for their needs. This search has seen the rise in popularity of gold loans, a financial option that has existed for centuries but has recently gained renewed attention. In this article, we’ll explore what a gold loan is, how it works, and why it might be the right option for you.
What Is a Gold Loan?
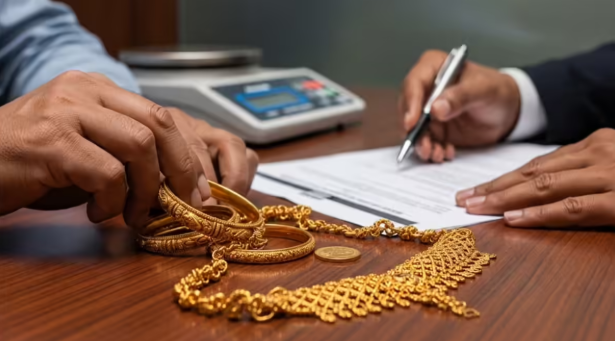
A gold loan is a secured loan offered by various financial institutions, where gold ornaments or bullion serve as collateral. Simply put, when you pledge your gold to a lender, you receive a loan amount that is a percentage of the gold’s current market value. This financial solution caters to those who may not have a perfect credit history but own gold assets.
The unique aspect of a what is gold loan lies in its simplicity and ease of access. Unlike traditional loans that require extensive documentation and a good credit score, gold loans are much less complicated. This makes them an appealing choice for many people who may need quick access to funds.
The Basics of How Gold Loans Work
To better understand how gold loans work, it’s important to break down the process into a few essential steps:
- Evaluation of Gold: When you approach a lender for a gold loan, they will first evaluate the purity and weight of your gold. The more refined and heavier your gold item, the more value it can fetch.
- Loan-to-Value Ratio (LTV): Once the evaluation is complete, the lender establishes a loan-to-value ratio, typically ranging from 60% to 90%. For instance, if your gold jewelry is worth ₹100,000 and the LTV is set at 75%, you can borrow ₹75,000.
- Documentation: Despite the process being relatively simple, some documentation is needed. You may be required to present identification proof, address proof, and sometimes a photograph of the gold item.
- Loan Disbursement: After all the formalities are verified, the lender disburses the loan amount, usually on the same day. The loan repayment terms and interest rates will also be discussed at this stage.
- Repayment: Borrowers are required to pay back the loan along with interest within the stipulated time. Gold loans typically have flexible repayment options, including full payment or equated monthly installments (EMIs). Upon successful repayment, the lender returns the pledged gold to the borrower.
Advantages of Gold Loans
Gold loans hold several advantages that make them a preferred option for many:
- Quick Access to Funds: Unlike unsecured loans that may take days or even weeks for processing, gold loans are usually processed within hours. This is especially advantageous in emergency situations.
- Minimal Documentation: The documentation process is straightforward, largely due to the loan being secured by collateral. This reduces the burden on borrowers.
- Flexible Repayment Options: Lenders offer various repayment plans, allowing borrowers to choose the most suitable option for their financial situation. Some might prefer to pay back the full amount at once, while others may find EMIs more manageable.
- No Impact on Credit Score: Since gold loans do not require a credit score check, they provide financial assistance to individuals with a poor credit history without adversely affecting their credit rating.
- Possibility of High Loan Amounts: Due to the high value of gold, borrowers can acquire substantial loan amounts, which may not be possible with unsecured personal loans.
Disadvantages of Gold Loans
Despite the numerous advantages, gold loan may not be an ideal solution for everyone. Here are some potential downsides:
- Risk of Losing Assets: If borrowers are unable to repay the loan within the agreed timeframe, they risk losing their pledged gold. This makes it crucial for borrowers to consider their repayment capabilities beforehand.
- Interest Rates: While gold loans tend to have lower interest rates than unsecured loans, the rates can still be high compared to some other secured loan options. Thus, borrowers need to shop around and compare rates.
- Market Volatility: The value of gold fluctuates. If the market value of gold decreases significantly, lenders may demand additional collateral from borrowers to secure the loan.
- Limited Use of Funds: Some lenders may restrict the use of funds obtained through a gold loan, meaning borrowers need to keep the spending purpose in mind.
How to Choose a Gold Loan Provider
Selecting the right lender for your gold loan is critical. Consider the following factors to make an informed choice:
- Interest Rates: Compare the interest rates offered by different lenders. A lower rate can save you a significant amount in the long run.
- Loan-to-Value Ratio: Look for lenders who provide a higher LTV ratio, as this will allow you to borrow more against your gold.
- Repayment Flexibility: Different lenders offer varied repayment options. Choose the one that aligns with your financial strategy.
- Customer Reviews: Research customer feedback and reviews for potential lenders. Good service can go a long way during the loan repayment process.
- Hidden Charges: Ensure that there are no hidden fees such as processing charges or penalties for early repayment. Transparency is key.
Conclusion
In summary, a gold loan can be an effective way to secure quick funding when needed. By pledging your gold assets, you can potentially unlock substantial financial resources without the stringent requirements of traditional loans. While there are risks involved, understanding how gold loans work and evaluating your options can set you on a path to making an informed decision.
If you find yourself in need of urgent funds for medical emergencies, business ventures, or educational expenses, exploring the gold loan route might be worth considering. Always weigh the pros and cons, assess your repayment ability, and choose your lender wisely. With careful planning and consideration, a gold loan may just be the financial solution you are looking for!
More Stories
Top Benefits of Choosing Custom Product Boxes Today
How Smart Startup Valuation Creates Equity, Tax, and Growth Advantages
Practical steps for publishers to balance editorial control and AI automation amid safety debates