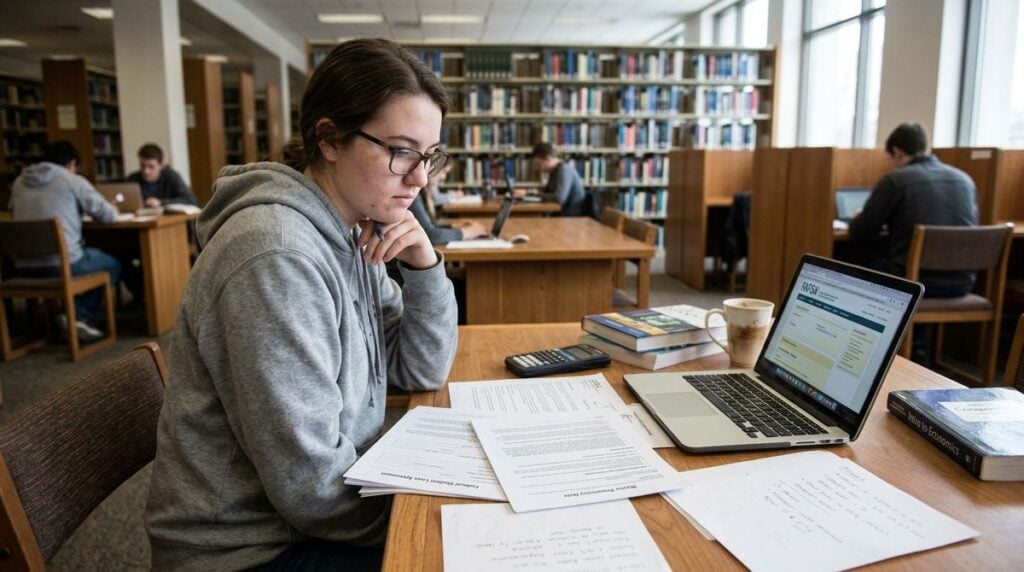
Many graduates leave university with student loan balances that they must start repaying in a particular way. Statements can arrive by post, email, or through an online account, and they may use terms that are unfamiliar. Missing a due date can create extra charges or stress, even when the amount owed is manageable. This article explains a simple tracking system that helps you stay on schedule. It offers general information only, and the details of your own loan agreement always take priority.
Gather your loan details in one place
Start by collecting the key facts about each loan. Note the name of the organization that manages it, the account reference, the repayment start date, and the way payments are collected. Some loans are repaid through an employer deduction, while others involve direct payments. Write down whether you receive statements electronically or by post, since this affects how you will stay informed.
If you have more than one loan, keep a separate record for each. It also helps to note who to contact for each loan, including the phone number, the opening hours, and any secure messaging option the organization provides. Having these details ready makes a difficult call far easier. Mixing them up can lead to confusion about balances and repayment dates. A simple table in a notebook or document can show each loan side by side, which makes review much easier.
Set reminders that fit your routine
A due date is only useful if you remember it. Set reminders in your calendar or phone a few days before each statement is expected, and another reminder on the day of payment. If you are paid monthly, place the reminder just after your salary arrives, when you are most likely to plan your spending. Choose one reminder style and stick with it, rather than creating many alerts that become easy to ignore. If your income is irregular, set the reminder for a day when you know your balance will be strongest, and review the upcoming statement a few days early.
Readers may also want to visit Mama hustler. Reading these guides before you need them can reduce anxiety when a statement arrives.
Read the statement carefully
Statements often contain several figures, including the outstanding balance, interest added, repayments made, and the next expected date. Look for the summary section first, then check the detail. Compare the repayment amount with your employer’s deductions if they apply, and make sure your personal details are correct. If anything seems unusual, contact the organization that manages your loan before assuming there is an error.
Keep a copy of each statement in a secure folder, either on paper or as a digital file. Over time, these records show your progress and help you resolve questions if a payment is missed or recorded incorrectly. Store them somewhere private, since they contain sensitive information. If a figure on a statement is unclear, write down the exact wording and the date, then ask for a plain explanation. Keeping your questions in writing makes it easier to follow up later.
Use a simple tracking system
A tracking system does not need to be complicated. Many people use a monthly checklist:
1. Confirm the expected repayment date for each loan.
2. Check that the amount deducted or paid matches the statement.
3. Note any changes in income that might affect your repayment amount.
4. Save the statement and record the reference number.
5. Mark the next review date in your calendar.
Review your system every few months, and update it when your job, address, or contact details change. You can also visit Buienradar for more reading. Notify the loan organization of changes promptly, since out-of-date information can cause missed messages. If you are unsure which details to update, ask for written confirmation of what they hold on file.
Speak early if repayment becomes difficult
If you are worried that you cannot make a payment, contact the loan organization as soon as possible. Many organizations offer options when they are told about a problem early, such as temporary arrangements or a review of your circumstances. Waiting until a payment is already overdue can make the situation harder to resolve. Be honest about your income and expenses, and ask exactly what options are available. Keep any letters you receive, even ones that seem routine, because they show what was communicated and when.
For personal guidance, a qualified financial adviser or a free debt advice service can help you understand the choices available. For a related read on this site, see Writing a Cover Letter That Explains an Overseas.
Taking action early protects your credit history and your peace of mind, and it gives you more control over the months ahead.
More Stories
Setting Aside Money for School Holiday Childcare Costs
Building a Pet Expense Log That Makes Year-End Records Easier to Review
Handling Unexpected Bills During a Big Life Event Without Panic