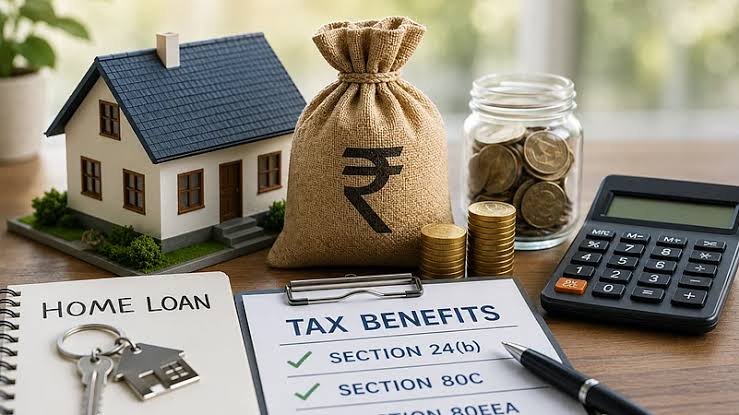
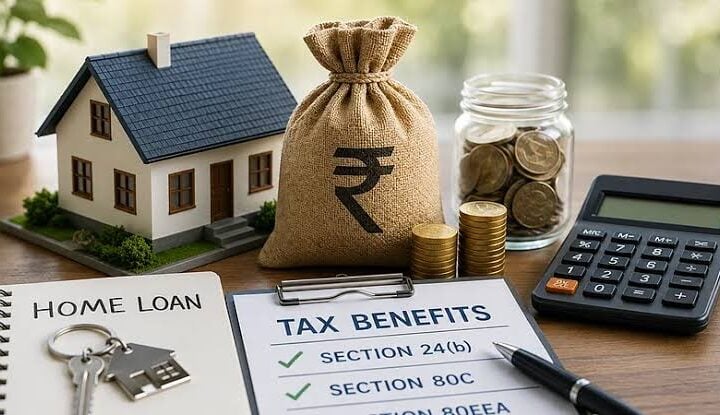
Buying a home usually involves a substantial financial commitment, but the repayment of a housing loan may also come with certain tax advantages. Understanding the home loan tax benefit can therefore help borrowers look at their loan from a broader financial-planning perspective rather than concentrating only on the monthly EMI. A typical home loan repayment includes both principal and interest, and these components may receive different tax treatment when the prescribed conditions are satisfied. However, the benefits available depend significantly on the tax regime selected by the taxpayer, the nature of the property, and the purpose for which the loan was taken. This makes it important to understand the applicable provisions before estimating possible savings. Alongside tax planning, borrowers can use a home loan EMI calculator to understand their monthly repayment commitment and compare different loan scenarios. Similarly, keeping the documents required for an affordable home loan organised can make it easier to maintain repayment and interest records that may later be useful while preparing tax-related information.
Home Loan Tax Benefit: Principal and Interest Are Treated Differently
The home loan tax benefit is linked primarily to the principal and interest portions of eligible loan repayments. Under the old tax regime, qualifying principal repayment can form part of deductions available under Section 123, while eligible interest on a self-occupied property may be considered under Section 22.
Here is a simple overview:
| Home Loan Component | Relevant Provision | Broad Treatment Under Old Tax Regime |
|---|---|---|
| Principal repayment | Section 123 | Included within the overall Rs. 1.5 lakh combined limit |
| Interest on eligible self-occupied property | Section 22 | Up to Rs. 2 lakh, subject to applicable conditions |
| Interest for certain repairs | Section 22 | Lower limits may apply |
It is important to note that the Rs. 1.5 lakh Section 123 limit is shared with other eligible investments and payments. It is not an additional limit reserved exclusively for home loan principal repayment.
Section 123: Where Principal Repayment Fits In
For eligible taxpayers following the old tax regime, the principal portion of a home loan repayment may qualify within the overall Section 123 deduction limit.
However, borrowers should avoid treating every rupee of principal repayment as an automatic tax saving. The available deduction may depend on how much of the Section 123 limit has already been used for other eligible payments or investments.
Therefore, when estimating a home loan tax benefit, look at your overall tax position rather than considering the loan in isolation.
Section 22: Understanding the Interest Advantage
Interest usually represents a significant portion of home loan repayments, particularly during the earlier years of the loan.
For an eligible self-occupied property under the old tax regime, interest on borrowed capital for purchase or construction may qualify for a deduction of up to Rs. 2 lakh, subject to the prescribed conditions.
This is one reason it is useful to retain the interest certificate or annual loan statement provided by the lender. These records can show how much interest was paid during the relevant financial year.
Your Tax Regime Can Change the Picture
One of the most important considerations is whether you follow the old or new tax regime.
For a self-occupied property, the deduction for interest on borrowed capital under Section 22 is not available under the new tax regime. Taxpayers wishing to claim the eligible deduction for a self-occupied property generally need to evaluate whether the old regime is suitable for their circumstances.
Consequently, choosing a tax regime solely because you have a housing loan may not always be sensible. Compare your complete taxable income, deductions, and applicable tax liability under both alternatives.
Use a Home Loan EMI Calculator to Understand Repayment
A home loan EMI calculator can help you estimate how much you may need to repay each month based on:
- Loan amount
- Interest rate
- Repayment tenure
Although the calculator does not calculate your final tax deduction, it can help you understand the broader repayment structure.
For instance, a longer tenure may lower the monthly EMI but could result in more interest being paid over the life of the loan. Therefore, tax savings should not be used as the main reason for deliberately increasing interest expenditure.
Keep Your Affordable Home Loan Documents Required for Records
The documents required for an affordable home loan may vary according to the lender and applicant profile, but certain loan-related records can also be useful when organising tax information.
Consider retaining:
- Loan sanction letter
- Annual interest certificate
- Repayment statement
- Property ownership documents
- Payment records
- Completion-related documents, where applicable
Keeping these documents organised can make it easier to identify the principal and interest amounts relevant to your tax calculations.
Avoid Viewing Tax Benefits as “Free Money”
A deduction reduces eligible taxable income; it does not reimburse the entire amount paid as EMI or interest.
Therefore:
- Do not borrow more simply to increase a deduction
- Compare tax savings with total interest expenditure
- Choose an EMI that fits your regular budget
- Maintain sufficient emergency savings
- Verify which deductions apply to your tax regime
The objective should remain sustainable homeownership rather than maximising deductions.
Summary: Make the Home Loan Tax Benefit Part of Wider Planning
The home loan tax benefit can provide useful tax advantages to eligible borrowers, particularly through provisions covering principal repayment and interest under the old tax regime. However, the actual benefit depends on applicable conditions and the tax regime chosen.
A home loan EMI calculator can help you understand repayment before borrowing, while keeping the documents required for an affordable home loan properly organised can support smoother financial record-keeping.
Ultimately, tax benefits should complement a sensible home financing decision rather than drive it. Understanding repayment, overall interest cost, and available deductions together can help you plan your home loan more effectively.
More Stories
Red Sea shipping attacks sharpen the case for broader portfolio risk tools
Everything You Need to Know About Gold Loan Interest Rates in Gujarat
Hybrid Mutual Funds for Investors Who Want Growth With Stability